
China’s Equipment Localization Rate at 55%: The Mature Node Milestone
A semiconductor factory can become substantially more local without becoming entirely independent. Domestic etch chambers may operate alongside imported lithography systems. A locally assembled deposition tool may still rely on overseas components. An expanding packaging operation may use a different supplier mix from the wafer fab feeding it.
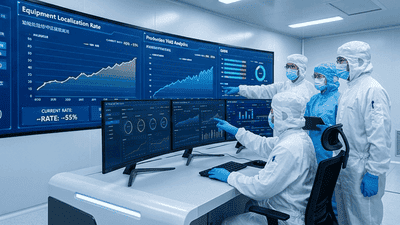
That is the context needed to evaluate the claim that China’s equipment localization rate has reached 55%. The figure could not be verified as a comprehensive national rate across semiconductor equipment. A narrower mature-node purchasing basket, selected production line, or particular equipment category could produce a higher percentage than the overall market, but that requires a clearly defined basis.
For this discussion, 55% is therefore an illustrative mature-node milestone rather than an established nationwide statistic. Its strategic significance lies in depth: whether domestic suppliers are becoming dependable participants across a production flow, not merely appearing in a larger number of equipment catalogs.
The Broader Market Provides a Different Benchmark
A broad industry assessment placed China’s semiconductor equipment localization rate at 23.2% in 2025, with a projection of 39% by 2030. It also described faster progress in mature-node and specialty segments than across the market as a whole. Those figures do not rule out a higher share in a narrower application, but they do not establish the requested 55% national headline.
The distinction is fundamental. An industry-wide estimate and a selected fab’s procurement result answer different questions.
One describes the broader competitive landscape. The other may show how far a particular customer has progressed in qualifying local alternatives. Both can be useful, provided they are not presented as interchangeable.
For investors and manufacturers, the first task is therefore to identify the denominator before interpreting the percentage.
What Does Localization Actually Measure?

Equipment localization can be measured by purchasing value, shipment units, installed systems, or the share of process steps supported by domestic platforms. Each measure emphasizes a different aspect of progress.
A purchasing-value metric can be influenced heavily by a few expensive tool categories. A unit-count metric can give greater weight to less costly systems. Neither necessarily indicates whether a complete line can operate independently.
The supplier definition also matters. Domestic branding, local assembly, domestic engineering, and a fully local component chain are different conditions.
A credible 55% milestone would therefore specify the relevant node range, equipment categories, period, measurement method, and treatment of imported components. Without those details, the number offers more rhetorical confidence than operational insight.
Why Mature Nodes Are a Practical Localization Arena
Mature-node manufacturing serves products whose commercial value depends on reliability, cost, analog behavior, power handling, or specialized functions rather than the smallest transistor dimensions.
These processes can offer local equipment suppliers a practical development environment. Requirements may be well characterized, and customers can evaluate alternatives against established production histories.
However, mature does not mean easy. A power device or industrial chip can have demanding process and reliability requirements. A replacement tool still needs to produce acceptable results consistently.
The advantage is a more manageable qualification boundary in selected applications. Suppliers can concentrate on a defined process, gain operating experience, and expand from demonstrated success rather than attempting to reproduce an entire advanced manufacturing platform immediately.
Etch and Deposition Create Visible Openings

China’s equipment progress is uneven across process categories. Industry assessments identify etching, deposition, and CMP among the areas gaining domestic participation, while other capabilities remain more difficult to localize broadly.
This unevenness explains how a mature-node procurement basket could reach a relatively high local share without establishing the same result across every equipment family.
A customer may qualify domestic platforms for several material-removal and film-formation steps while retaining imported tools elsewhere.
For equipment suppliers, that creates a credible growth path. For analysts, it creates a warning against extrapolation: success in one process category cannot be converted automatically into equivalent progress in lithography, implantation, inspection, or the complete manufacturing line.
Cleaning and CMP Matter Beyond Their Visibility
Cleaning and planarization receive less public attention than lithography, but they contribute directly to the conditions required for subsequent processing.
A local cleaning platform needs to remove unwanted material without damaging the wafer or introducing unacceptable variation. A CMP platform must operate with qualified pads, slurries, and process settings.
These applications illustrate why equipment localization is not separate from materials qualification. A machine’s performance depends on what it processes and the consumables used with it.
From a factory manager’s perspective, the relevant question is whether the complete process combination works. From an investor’s perspective, additional tool sales are more meaningful when customers can repeat that performance across production lots and expansion projects.
Lithography Can Keep the Percentage Below the Capability
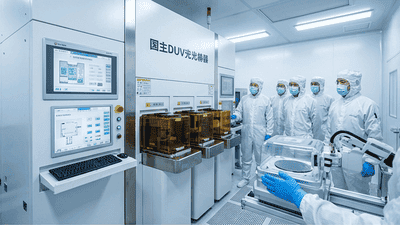
A fab may localize many process steps while remaining dependent on imported lithography equipment. Because lithography is commercially significant and technically demanding, that dependence can strongly influence purchasing-value measures.
The opposite issue can arise with unit counts. Numerous locally supplied systems can raise the unit share even when one critical imported platform remains essential to the line.
Neither result is inherently misleading, but each needs interpretation. The percentage describes a purchasing or installation pattern, not necessarily the ability to manufacture without external supply.
For mature-node projects, established imported platforms may continue operating alongside domestic alternatives. That mixed configuration can be commercially rational while still leaving important lifecycle and support dependencies.
Qualification Is the Real Milestone
A domestic tool becomes strategically useful when it performs a customer’s process reliably, not simply when it is delivered to the factory.
Evaluation can involve process results, repeatability, handling, maintenance, throughput, and integration with the surrounding line. The customer needs confidence that the equipment will remain usable beyond a successful demonstration.
Initial approval may also be narrow. A system qualified for one recipe or device family should not be assumed suitable for every application within the same nominal node.
The strongest milestone is recurring adoption: customers reorder the platform, expand its qualified uses, and operate it without excessive intervention. That evidence says more about localization progress than a target announced before production begins.
Repeat Orders Reveal a Different Kind of Confidence
A first purchase can reflect interest, policy incentives, or a development partnership. A repeat purchase suggests that the customer sees enough practical value to increase exposure.
Even then, context matters. Additional orders from one customer do not establish universal acceptance, and purchases may remain concentrated in one process.
Broader adoption across facilities and applications provides stronger evidence that a supplier has developed a reproducible business.
For investors, the important progression runs from evaluation to qualified use, then to repeat orders and sustained service. Revenue growth becomes more convincing when it follows that operating evidence rather than depending mainly on initial installations.
Local Systems Can Still Contain Global Dependencies
A domestic equipment platform may incorporate overseas vacuum pumps, RF generators, sensors, motion systems, control electronics, or specialized ceramic assemblies.
This does not invalidate the platform’s local engineering contribution. It means complete-tool localization and upstream independence should be assessed separately.
For the customer, a critical component dependency can affect delivery, maintenance, and future expansion. For the equipment supplier, it can limit how quickly production scales.
A mature-node milestone becomes more resilient when the component chain develops alongside the final equipment. The appropriate question is not whether every part is local, but which remaining dependencies could interrupt production and whether workable alternatives exist.
The Back End Has Its Own Localization Path
Assembly, packaging, and testing should not simply be added to a front-end percentage without explanation. Their equipment requirements and competitive structures differ.
Established assembly processes can create opportunities for local bonders, molders, handlers, and test-related platforms. Advanced packaging can introduce additional demands for alignment, wafer-level processing, inspection, and thermal control.
Progress in conventional packaging therefore does not prove readiness for every advanced integration application. Equally, a specialized advanced-packaging success may not describe the broader assembly market.
A meaningful localization dashboard separates these activities. It shows which capabilities are qualified, where capacity is expanding, and how front-end output connects to usable packaged devices.
A Higher Local Share Changes Supplier Economics
If a defined mature-node purchasing basket reached 55% domestic sourcing, the commercial consequences could be substantial. Local suppliers would participate more deeply in recurring expansion, service, and replacement activity.
Customers could gain additional negotiating options and reduce dependence on individual overseas platforms. Suppliers could accumulate application knowledge from a larger installed base.
However, market share alone does not establish profitability. Aggressive pricing, customization, field-support costs, and development spending can reduce the financial benefit.
For investors, the useful test is whether greater participation produces sustainable margins and cash generation. A strategically important equipment company can still have a difficult business model if each installation requires excessive engineering effort.
Service Capability Determines Whether the Share Lasts
A tool’s commercial relationship continues after acceptance. Maintenance, spare parts, troubleshooting, and process changes all affect the customer’s experience.
Local proximity can help, but response speed matters only when supported by technical competence and available parts.
As suppliers expand, they need to build field organizations without losing control of costs or consistency. That requirement can become especially demanding when customers operate different configurations.
For a fab, a dependable domestic service network can be an important advantage. For a supplier, it is part of the investment required to turn initial market access into a durable installed-base position.
Capacity Expansion Can Expose Weaknesses
Rapid growth creates operational pressure. A supplier must secure components, train personnel, maintain quality, and complete testing at a larger scale.
Customers face their own challenge: installing multiple platforms while preserving production stability. Introducing too many unproven changes simultaneously can make troubleshooting more difficult.
A higher localization target should therefore be paired with realistic deployment planning. The objective is usable capacity, not maximum domestic content regardless of operating consequences.
This is where mature-node experience becomes valuable. Controlled adoption and accumulated production evidence can support expansion more effectively than treating every new project as an opportunity to replace every imported system.
What a Credible 55% Claim Would Require
The headline becomes useful when it is accompanied by a transparent methodology.
- Define whether the figure concerns national purchases, selected fabs, or particular processes.
- Identify the mature-node range and equipment categories included.
- Specify whether the measure uses value, units, or installed capacity.
- Explain how local assembly and imported subsystems are treated.
- Separate deliveries from qualified production deployment.
- Provide a consistent period for comparing progress.
Those details do not diminish the milestone. They establish what has actually changed and which conclusions can reasonably follow.
What Investors and Buyers Should Watch Next
The strongest indicators combine adoption with performance: repeat orders, expanding qualified applications, stable uptime, and improving support capability.
Buyers should examine total operating cost and the availability of maintenance throughout the tool’s life. Investors should examine customer concentration, working capital, and the cost of supporting a growing installed base.
Both should distinguish broad localization ambitions from application-specific evidence. The market can advance rapidly in selected categories while remaining dependent elsewhere.
A useful forecast therefore follows the process map. It asks where local suppliers are becoming competitive, which capabilities remain constrained, and whether the complete line can operate economically.
The Mature-Node Milestone Is Operational, Not Numerical
China’s equipment localization is progressing, especially in selected mature-node and specialty applications. But the requested 55% should not be presented as a verified comprehensive rate without a matching scope and methodology.
As an illustrative milestone, it describes a meaningful transition: domestic suppliers taking responsibility for a larger share of production requirements.
The lasting achievement is not crossing a percentage threshold. It is building tools that customers qualify, operate, support, and order again. That is how localization becomes dependable manufacturing capability.